The Debt Beneath the Surface: Why Japan's Fiscal Crossroads Could Send Shockwaves Through US Markets
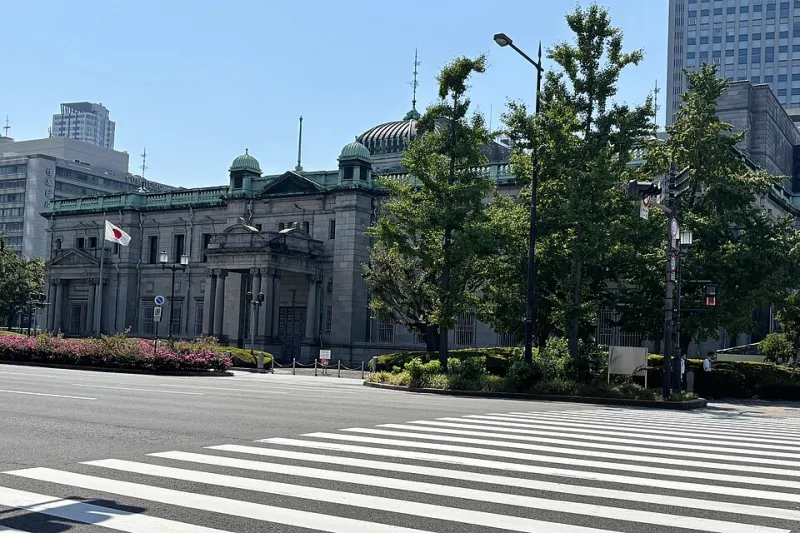
Photo: Sakai Yayoi, CC0, via Wikimedia Commons
A Reckoning Decades in the Making
For most of the past three decades, Japan's fiscal situation has functioned as a kind of economic paradox — a debt burden so large that conventional theory suggested crisis was imminent, yet so stubbornly stable that markets eventually stopped paying attention. That inattention may now carry a price. As the Bank of Japan (BOJ) edges away from the yield curve control policies that have suppressed borrowing costs since 2016, a set of structural fiscal pressures that American investors have long discounted is beginning to surface in ways that matter to portfolios far beyond Tokyo.
Japan's gross public debt stands at approximately 260 percent of GDP — a figure that dwarfs every other major advanced economy, including the United States, which itself sits at roughly 120 percent. The reasons Japan has managed this burden without the sovereign debt crisis that similar ratios would likely trigger elsewhere are well documented: domestic ownership of government bonds, a captive savings base channeled through institutional investors, and a central bank willing to absorb unlimited quantities of Japanese Government Bonds (JGBs) to keep yields near zero. Each of those stabilizing factors is now under some form of stress.
The BOJ's Delicate Pivot
The Bank of Japan's decision in late 2023 to loosen its yield curve control framework — allowing the 10-year JGB yield to drift above 1 percent for the first time in over a decade — was widely interpreted as a technical adjustment. In practice, it signaled something more consequential: the beginning of a normalization process that Governor Kazuo Ueda has been careful not to describe as tightening, but which carries tightening's essential logic.
For Japan's fiscal arithmetic, even modest rate increases are significant. The government currently spends roughly 8 percent of its annual budget on debt servicing at near-zero rates. Independent estimates from the Japanese Ministry of Finance and outside analysts suggest that a sustained 1 percentage point increase in average borrowing costs could add the equivalent of $70 to $90 billion annually to debt service obligations within a decade, as existing bonds mature and are refinanced at higher rates. In a country where social security expenditures are already consuming an expanding share of the budget due to demographic aging, that is not a marginal adjustment.
The Carry Trade Unwinding Risk
For American investors, the most immediate transmission mechanism from Tokyo to their portfolios runs through the yen carry trade — one of the most enduring and heavily utilized strategies in global currency markets. For years, institutional investors have borrowed cheaply in yen, converted those funds into higher-yielding assets including US Treasuries, equities, and corporate bonds, and pocketed the spread. The strategy works elegantly as long as the yen remains weak and Japanese rates stay near zero.
A sustained BOJ rate-hiking cycle — even a shallow one — threatens to unwind this trade at scale. Yen appreciation would erode the returns on dollar-denominated assets held by carry traders, potentially triggering a rapid liquidation of US Treasury positions. The August 2024 episode, in which a partial BOJ rate adjustment contributed to a brief but violent global equity selloff and a sharp yen rally, offered a preview of the dynamic. Market participants who dismissed that episode as a technical correction may be underestimating its diagnostic significance.
The US Treasury market, already navigating elevated supply issuance and shifting Federal Reserve policy, is poorly positioned to absorb a large-scale withdrawal of Japanese institutional demand without meaningful yield consequences. Japan remains one of the largest foreign holders of US government debt, with holdings exceeding $1.1 trillion as of recent Treasury International Capital data.
Corporate Earnings in the Crossfire
Beyond sovereign debt dynamics, Japan's fiscal evolution carries direct implications for the earnings of US multinational corporations with significant Japanese revenue exposure. A stronger yen — the likely byproduct of BOJ normalization — cuts both ways. American companies that manufacture in Japan and sell in dollars benefit from yen weakness; those that earn yen revenues and repatriate them to the United States face translation headwinds when the yen strengthens.
Technology sector exposure deserves particular attention. Several major US semiconductor and enterprise software firms generate between 10 and 15 percent of global revenues from Japan, a market that has historically been sticky and premium-priced. Currency volatility at the scale that a BOJ normalization could introduce would complicate earnings guidance and potentially suppress capital expenditure commitments by Japanese corporate clients navigating their own balance sheet pressures.
American investors holding positions in firms such as Applied Materials, KLA Corporation, or enterprise software providers with deep Japanese client bases should be modeling yen sensitivity scenarios that go beyond the consensus range.
Fiscal Reform Signals to Watch in 2025
The Japanese government under Prime Minister Fumio Kishida's successors has articulated a commitment to fiscal consolidation, but the political constraints are formidable. The ruling Liberal Democratic Party faces an electorate that is simultaneously resistant to consumption tax increases and dependent on the social welfare programs those revenues would fund. The 2025 budget cycle will be a critical test of whether Tokyo can demonstrate credible medium-term fiscal discipline without triggering a domestic demand contraction.
Key indicators for American investors to monitor include: the trajectory of the 10-year JGB yield relative to the BOJ's implicit tolerance band; the pace of foreign institutional reallocation out of JGBs; and any signals from the Ministry of Finance regarding the issuance calendar for long-dated bonds. A material increase in 30-year JGB issuance, for instance, could signal that the government is attempting to lock in current rates before normalization accelerates — a move that would itself put upward pressure on global long-duration yields.
The Systemic Connection American Investors Cannot Ignore
Japan's fiscal situation is not a crisis in the conventional sense — there is no imminent default risk, and the domestic institutional framework that has sustained JGB demand for decades has not collapsed. What is changing is the margin of error. The combination of rising domestic rates, an aging population drawing down savings rather than accumulating them, and a central bank that can no longer credibly commit to unlimited bond purchases creates a narrower path for fiscal management than Japan has navigated in recent memory.
For American investors, the relevant question is not whether Japan will experience a sovereign debt crisis, but whether the gradual normalization of Japanese monetary and fiscal conditions will introduce a persistent source of volatility into US bond and equity markets that current valuations do not reflect. The evidence suggests the answer is yes — and that the time to incorporate that variable into portfolio construction is before, not after, the market decides to pay attention.